Construction Finance Brokers in Melbourne
Building is financed differently to buying. A construction-savvy broker sets up the right loan, manages the progress-payment drawdowns and lines up the Victorian grants and schemes you qualify for.
Loan type
Construction
drawn in stages
Stages
5 typical
slab to completion
FHOG (VIC)
$10,000
new homes, conditions apply
Scheme
Homebuyer Fund
VIC shared equity
Why a construction loan is different
A construction loan releases money in stages (deposit, base/slab, frame, lock-up, fixing and completion) and you usually pay interest only on the amount drawn so far. The lender values against the fixed-price building contract and the land, and releases each progress payment after the work for that stage is done.
A broker who does a lot of construction lending knows which banks handle fixed-price contracts, owner-builders, knockdown-rebuilds and house-and-land splits smoothly, and which will slow your build down. That choice matters more than a headline rate.
Grants and schemes a Melbourne broker lines up
For eligible new builds your broker helps you claim the First Home Owner Grant and apply any stamp-duty concessions, and can assess the Victorian Homebuyer Fund (the state shared-equity scheme) and the federal First Home Guarantee where you qualify.
They also model Lenders Mortgage Insurance, your borrowing capacity against progress payments, and the cash you need at each stage, so there are no surprises when a drawdown is due.
What to check before you commit
Confirm the broker is licensed (an Australian Credit Licence holder or authorised credit representative) and ask how they are paid. Ask specifically how many construction loans they settle a year, because the process is where inexperience hurts.
Get pre-approval before you sign a fixed-price contract, and make sure the valuation, contract and any variations are handled so drawdowns are never held up mid-build. BuildPilot does not provide finance; we help you find a construction-experienced broker.
Official Victorian sources referenced
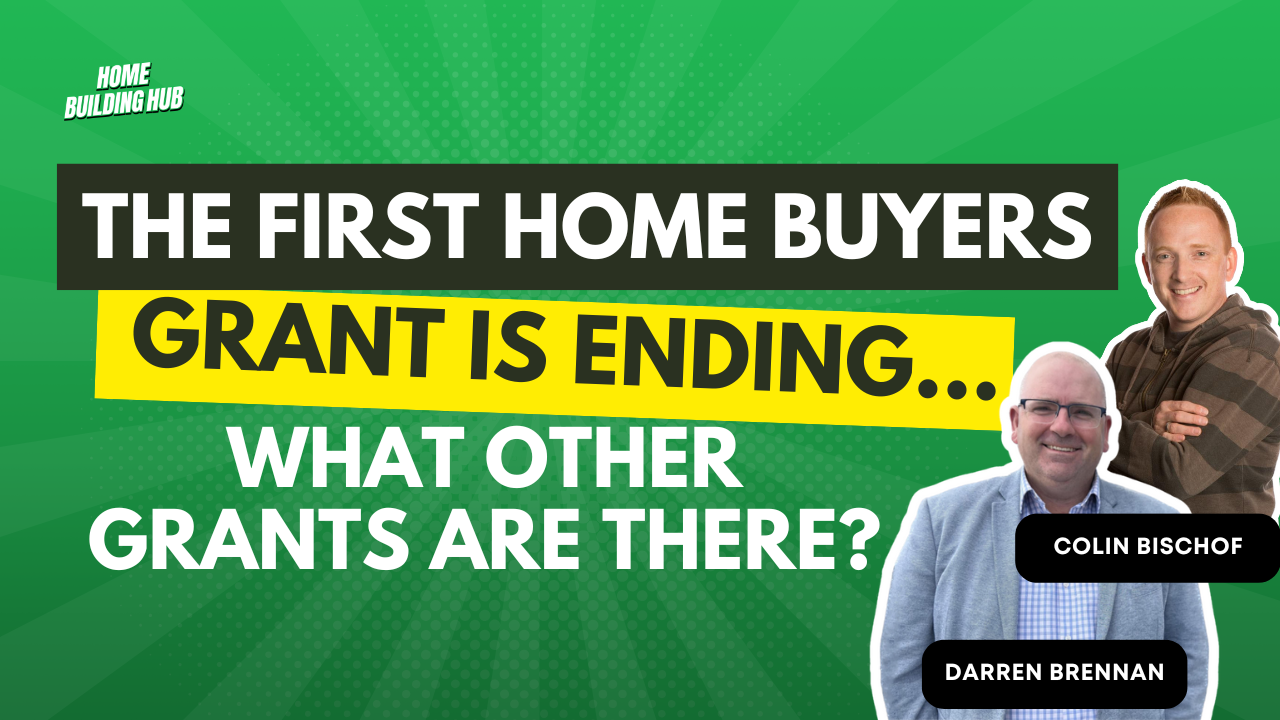
With the First Home Buyers Grant winding down, what help is still available? We break down the key grants and schemes you can still access, including shared equity options, stamp duty concessions, and home guarantee programs across Australia.
Watch full episodeFrequently asked
How is a construction loan paid out?+
In progress drawdowns tied to build stages, commonly slab, frame, lock-up, fixing and completion. You generally pay interest only on the amount drawn, and each payment is released after that stage is finished and sometimes inspected or valued.
Can a broker help with the First Home Owner Grant in Victoria?+
Yes. For eligible new homes the broker helps you claim the Victorian First Home Owner Grant and apply stamp-duty concessions, and can assess the Victorian Homebuyer Fund and the federal First Home Guarantee if you qualify.
Should I get pre-approval before signing a build contract?+
Yes. Pre-approval tells you your budget and avoids signing a fixed-price contract you cannot finance. It also lets the lender line up the valuation so your first drawdown is ready when the build starts.
Do finance brokers charge the borrower a fee?+
Many are paid commission by the lender at no direct cost to you, but some charge a fee for complex construction scenarios. Always ask how the broker is paid and get it in writing. Confirm they hold an Australian Credit Licence or are an authorised representative.
Note: the stories below are Adelaide-based clients - the underlying builder-matching process is identical for Melbourne buyers.
How our process runs - real client stories
Ochieng Residence
A first home buyer guided from land purchase through to a budget-friendly custom design in Morphett Vale.
Read the case studyFamily Extension Project
A staged renovation and extension in Gilles Plains, structured so the family could deliver parts of the home themselves.
Read the case studyBuilding in Adelaide instead?
See our Adelaide finance brokers guideCompare the options
The material and system choices that move your Melbourne build budget most, weighed up in plain English for Victoria.
Sources
Last verified June 2026- State Revenue Office Victoria, First Home Owner Grant link
- Victorian Homebuyer Fund link
- Housing Australia, First Home Guarantee link
Cost ranges are planning estimates cross-checked against the sources above, not quotes. Prices move with materials, labour, site conditions and council rules. Always confirm against a written, fixed-price quote for your own block.